The Autumn Budget will generate plenty of headlines. But for partners, senior executives, and other high earners, the most important questions are often more personal.
Article last updated 26 October 2026.
Article last updated 26 October 2026.
Foreword
The UK approaches this Budget with a new government and a new Chancellor in John Healey but a familiar challenge: how to strengthen the public finances without further weakening the investment and enterprise on which sustainable growth depends.
Across the country, our clients are building businesses, creating jobs, investing for the future and supporting their families and communities. Yet many tell us that repeated policy change, rising costs and uncertainty are making long-term decisions harder.
Stability matters, but stability alone is not enough: the UK also needs a clear, credible programme to unlock productive investment and reward aspiration.
This report – detailed below or available as a PDF download – applies a simple growth test to the choices facing the Chancellor. Will they increase the pool of long-term savings available to British businesses? Will they improve the incentive to invest, scale and list in the UK? Will they help people and capital move to where they can be most productive? And will they give regions the capacity to turn greater autonomy into stronger local economies?
Our recommendations are practical. They recognise the difficult trade-offs facing any government, but also the cost of continuing with a tax and regulatory system that too often discourages saving, investment and mobility. The central message is clear: the route to stronger public finances and higher living standards runs through investment-led growth. This is particularly true of the Prime Minister’s drive for devolution – without meaningful regional investment there is no reason to believe decentralising the state will drive growth.
Rathbones has long-term relationships with people and businesses – entrepreneurs, professionals and SME owners – across our 21 regional offices in the UK. We see both the ambition that exists and the barriers holding it back. By giving that experience a voice, supported by our economic analysis, we hope to contribute constructively to the choices ahead and to a policy environment in which more people can invest well, live well and help build the country’s prosperity.
Camilla Stowell
CEO Wealth, Rathbones
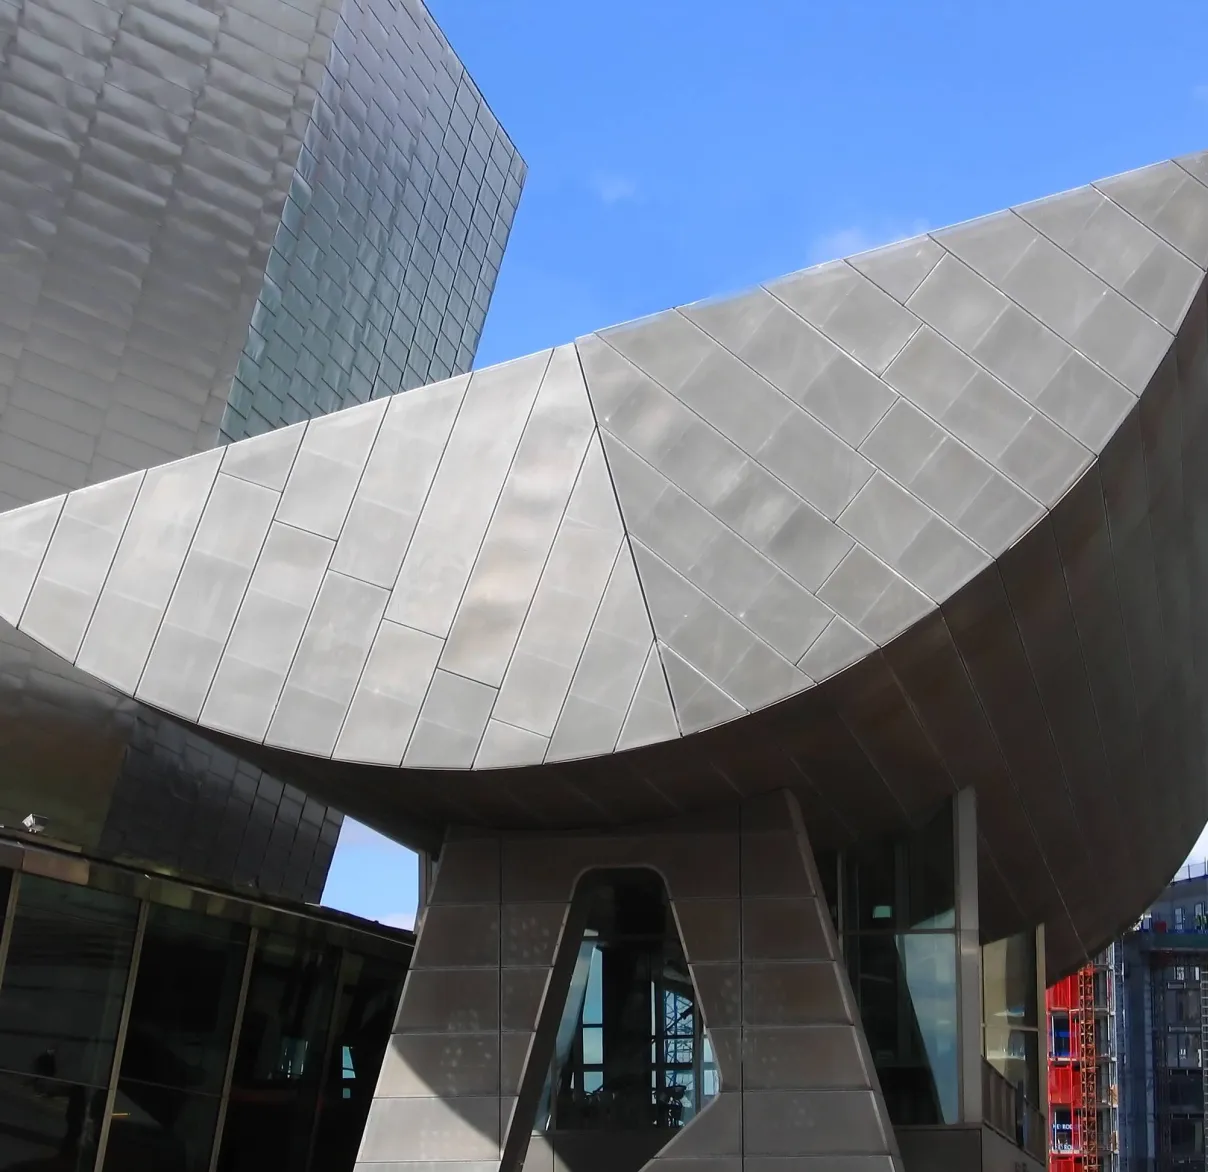
Our report's cover image shows The Lowry Arts Centre at Salford Quays, Greater Manchester, a place of regeneration from a declining docklands into a thriving cultural and economic hub.
Executive summary
The Chancellor faces a difficult fiscal backdrop, with higher borrowing costs eroding room for manoeuvre. But tax rises that weaken saving, investment or mobility risk reinforcing the cycle of low growth and pressure on the public finances.
The durable answer is to increase productive investment and the economy’s capacity to grow. In this second edition of Building prosperity (access the 2025 edition), our evidence-led view from the front line of entrepreneurship and enterprise, we focus on five areas where practical reform can support sustainable growth across the country.
Pensions, savings and productive investment
Avoid further restrictions on pension tax relief or the tax-free lump sum, and investigate abolishing Stamp Duty Reserve Tax so UK equities are not placed at a structural disadvantage.
Business taxation and competitiveness
Reform business rates so improvements are not penalised, maintain a stable corporation tax regime, and extend more generous capital allowances to buildings and intangible assets. Drive forward further planning reform and remove unnecessary regulation that discourages investment.
Property taxation
Begin a credible programme to reform or replace Stamp Duty Land Tax, improving use of the existing housing stock, labour mobility and construction activity.
Wealth taxes
Reject an annual wealth tax and approach any rise in capital gains tax with caution; if rates increase, reform the tax base to account for inflation and improve the treatment of investment losses.
Devolution
Treat increased local power as part of a wider growth programme that will not deliver growth unless it is seen as just one aspect of national prosperity.
These proposals are not a complete policy platform, but a set of practical changes that, based on what we see and hear from business people around the UK, would make the country a more attractive place to save, invest, build and grow.
Together, they could help build prosperity in every region while strengthening the long-term outlook for living standards and the public finances.
Overview
On 28 October, new Chancellor John Healey faces the unenviable task of delivering his first Budget. But while the occupant of Number 11 has changed, the vicious cycle of tax hikes and weak growth appears set to continue.
Our view on how to break that cycle is clear: the UK needs to step up its pursuit of investment-led growth. That is the best way to put the public finances on a more sustainable path and raise living standards. This report sets out our recommendations.
Since the Office for Budget Responsibility’s (OBR’s) latest forecast in March, the UK’s fiscal position has deteriorated as surging gilt yields have raised borrowing costs. This largely reflects conflict in the Middle East, with higher energy prices lifting expectations for inflation and interest rates. The benchmark 10-year gilt yield rose from around 4.5% when the previous forecast was made to about 5.4% by early October (figure 1).
In March, the OBR expected the government to meet its fiscal rule to balance day-to-day spending and revenue by 2029-30 with £24bn of ‘headroom’ – a margin for error. Recent estimates suggest roughly half of that buffer may have been eroded when the OBR runs the numbers again.
This is not necessarily an immediate problem. Rachel Reeves raised taxes at the last Budget partly to increase headroom and reduce the risk that future shocks would force course corrections. That decision has proved sensible given the impact of the Middle East conflict, although £24bn is not large by 2010s standards.
The Chancellor is therefore unlikely to need tax rises or spending cuts simply to meet the fiscal rules. But the rules are self-imposed and only rough guides to near-term sustainability; the long-run picture is more complex. Bond investors know this, so Healey may still need to err on the side of caution.
Like many advanced economies, the UK faces significant structural spending pressures. An ageing population is increasing demand for health and pensions, even after the tweak to the triple lock, while the working-age share of the population is shrinking. Geopolitical tensions require more spending on energy and food security and defence, and the end of ultra-low interest rates means higher debt-servicing costs.
Figure 1: UK 10-year government bond yield (%, 2026)
Recommendation 1 | Pensions, savings, and productive investment
For the UK economy to grow at a faster pace, it is imperative that the country’s most ambitious, dynamic, and innovative firms, and those who lead them, reach their full potential. In turn, that means the government needs to ensure they have access to the financing required to do so.
There is substantial evidence that high-growth firms (sometimes also referred to as ‘scale-ups’) play an outsized role in driving economic growth, through both creating employment and driving up productivity.4 However, data also suggest that part of the reason UK productivity growth has slowed since the Global Financial Crisis is because these firms have not been as successful in supplanting incumbents as their predecessors.5 In other words, business dynamism has fallen. Resources are not being reallocated to more productive firms as quickly.
There are numerous potential reasons why the UK economy has become less dynamic, ranging from the level of interest rates, to the tax system, to regulation and competition policy. While there is certainly more the government can do in many of these areas to boost dynamism, in the short term we think it is critical that it does not take action that exacerbates the problem by further disincentivising saving into pensions and limiting access to external financing.
Recommendation 2 | Business taxation and competitiveness
Ensuring an adequate supply of savings to support investment is one side of the equation. But firms need to want to invest, too. Andy Burnham has stated that he wants to give people “the confidence that if they have a great idea, they’ll get all the support they need to bring it to life.” The Chancellor has told his fellow G20 finance ministers that Britain is “a country whose people, and businesses and communities are ready to seize the opportunity of new technologies and new ideas.”
If the government is as serious about supporting investment and innovation as it claims to be, we think it should be focusing its efforts on a few key areas: business rates, capital allowances, and regulation.
Business rates have already been in the spotlight since Burnham took office in July. Indeed, in the Prime Minister’s first week, the government announced a cut to business rates for pubs, clubs, and live music venues in England from April 2027. This will be funded by a review of reliefs for firms that don’t make a “positive contribution” to local communities, such as vape shops.
While this cut is presumably popular with parts of the electorate and will be a helping hand to some businesses in the sector, it also introduces even more complexity to what is already a maze of reliefs and exemptions. And perhaps most importantly, we think it distracts from a more fundamental issue with the current business rates system.
The problem stems from the fact that business rates are levied on the estimated rental value of a property. If a business invests in improvements to its premises, increasing its rental value, then its tax burden rises too. That’s a clear disincentive to undertake upgrades to commercial property. In fact, a recent Confederation of British Industry survey of almost 700 firms found that nearly a third had cancelled, reduced, or delayed investment in their properties at least in part because of business rates.19
Recommendation 3 | Property taxation
Historical underinvestment in the UK isn’t limited to businesses. Investment in dwellings has been at or around the lowest in the G7 relative to GDP since at least 1985. The cumulative effect of this is the housing shortage the country finds itself in. Economic growth requires workers, yet we have failed to build sufficient homes in which they can live.
According to OECD data, England has 441 homes per 1,000 people. In Germany, there are 518 homes per 1,000 residents. In Spain, it’s 563. In France and Italy, the number is close to 600 (figure 5).26 Furthermore, the proportion of vacant houses is the second lowest of the twelve countries for which data is available, above only the Netherlands.
However, the shortage of supply is only part of the story. The UK is also inefficient in how it utilises its homes. The 2024-25 English housing survey found that 40% of properties are under-occupied (defined as having two or more bedrooms than required).27 Understandably, under-occupation is more common for the over-65s. Among those households, 58% are under-occupying, up from 53% ten years earlier – an increase of almost one million households.
For many, this is simply a lifestyle choice. However, plenty appear to be open to downsizing. Several polls over the past decade or so suggest that between a quarter and a half of older households are interested in the idea. And from an economic standpoint, it is sensible to make doing so as easy as possible.
Downsizing increases the supply of homes for younger, growing families to move into. On top of potentially improving the quality of day-to-day life for households on both sides of a transaction, it also allows working-age individuals to relocate more freely. This makes it easier for workers to find jobs where they are more productive. It also helps firms fill staff and skill gaps that are preventing them from growing. In other words, it improves labour mobility.
Figure 5: Dwellings per 1,000 inhabitants (2022 or latest)
Recommendation 4 | Wealth taxes
Last month, John Healey said he wants to see the UK as a “country of wealth creation”. In August, Burnham told the Financial Times that “we need wealth creation and the best wealth creators not just forging their path here, but staying here.” If those statements are sincere, they should ignore repeated calls to impose an annual wealth tax.
Ahead of the 2025 Budget, 53 MPs (including 26 Labour MPs and several former Labour MPs sitting as independents) signed a motion proposing a 2% annual wealth tax on individual assets over £10m. That same proposal is resurfacing ahead of this year’s Budget. The Compass thinktank, which has links to the Prime Minister, recently published policy proposals for the new administration, including that same 2% annual wealth tax on assets over £10m.33 Other organisations, such as campaign group Tax Justice UK, continue to back it, too.
While he has avoided publicly backing a wealth tax himself, Burnham said in a speech to Compass last year that “we have overtaxed labour and undertaxed wealth.” And when asked about the prospect of a wealth tax by Gary Lineker, the broadcaster, in an interview just before taking office, Burnham didn’t rule the idea out.
Consequently, it is worth restating the arguments we have made before for why imposing an annual wealth tax is a bad idea for a government looking to boost investment and growth. You can find out more in our 2025 report on the idea of a wealth tax.
Recommendation 5 | Devolution
Finally, it would be remiss to comment on the Burnham government’s plans without talking about devolution – the transfer of powers from central government to local and combined authorities – which is clearly at the heart of the Prime Minister’s policy agenda. While we think there are plenty of good reasons to pursue devolution in some form, we caution against relying on it as a silver bullet for the UK’s economic woes. It should be a complement to the recommendations made above, not a substitute.
One simple reason to devolve more powers to a local level is that voters want it. Polling suggests solid support for more devolved powers in areas where there are metro mayors.43 This should come as little surprise given that government in the UK is very centralised by international standards. In 2024, almost 92% of UK tax revenue was collected by central government. Meanwhile, 79% of spending was done by Westminster. That makes the UK one of the most fiscally centralised major advanced economies (figure 8).
It is possible that devolution, if executed well, could be positive for economic growth. For example, in certain policy areas such as transport or skills, local decision makers may be better placed to know what is best for growth in their area than those in Whitehall. Local government may also be able to co-ordinate across policy areas better than central government, in part because they are smaller, making cross-department communication potentially easier.
Additionally, reforms to funding models could provide more stability and facilitate better long-term planning. Councils and combined authorities currently rely heavily on central government grants, which can be short-term, uncertain, and tied to competitive bidding processes.
Experimentation is another possible benefit. Innovation isn’t limited to the private sector. If local governments are given sufficient freedom to pursue different policies, that will provide plenty of opportunities for ‘natural experiments’ to draw stronger conclusions on what works, and what doesn’t.
Figure 8: Central government tax revenue and expenditure as a share of total (2024, %)
Endnotes
If you would like to talk to one of our team about the announcements in the Budget and how we could help you make a plan, please fill in the form below and we'll get in touch. Alternatively, please feel free to call us on 0330 390 9191 and we’d be happy to help.
A typical Rathbones client has over £300,000 to invest or plan their financial future, including pensions but excluding property.
6 minutes
When you run your own business, your personal plans usually rise and fall with it. A Budget can change the detail. But knowing what you need from the business helps you understand whether your plans still add up and what, if anything, needs adjusting to keep them on track.